Lugano exits bankruptcy under new owner Middle West Partners and CEO Josh Gaynor
The Newport Beach jeweller has rebranded as Lugano Jewelry, with Gaynor confirmed from his interim role.


Lugano has reemerged from Chapter 11 with a new corporate name, Lugano Jewelry, new owners and Josh Gaynor as chief executive officer. The Newport Beach, California jeweller had entered bankruptcy in November under the weight of a scandal involving its founder, Mordechai Ferder, who resigned in May 2024.
The court-supervised sale closed late last month. Investment firm Middle West Partners, whose cofounder is Kevin Kelleher, bought the business alongside a group of the jeweller's longstanding clients. Gaynor had been serving as interim CEO and, before that, president, since Ferder's resignation.
Gaynor, who previously held senior roles at Bottega Veneta and Fendi, framed the exit as a fresh start. "This is a defining moment for Lugano," he said, crediting the team's commitment and client loyalty and promising to build on the relationships, values and standards of personal service that define the brand.
Kelleher said Lugano has earned its place in the luxury jewellery market through deep personal relationships with clients in key US markets. He cited its loyal client base, talented team and exceptional jewellery as a strong foundation for continued growth, and expressed confidence in its long-term potential.
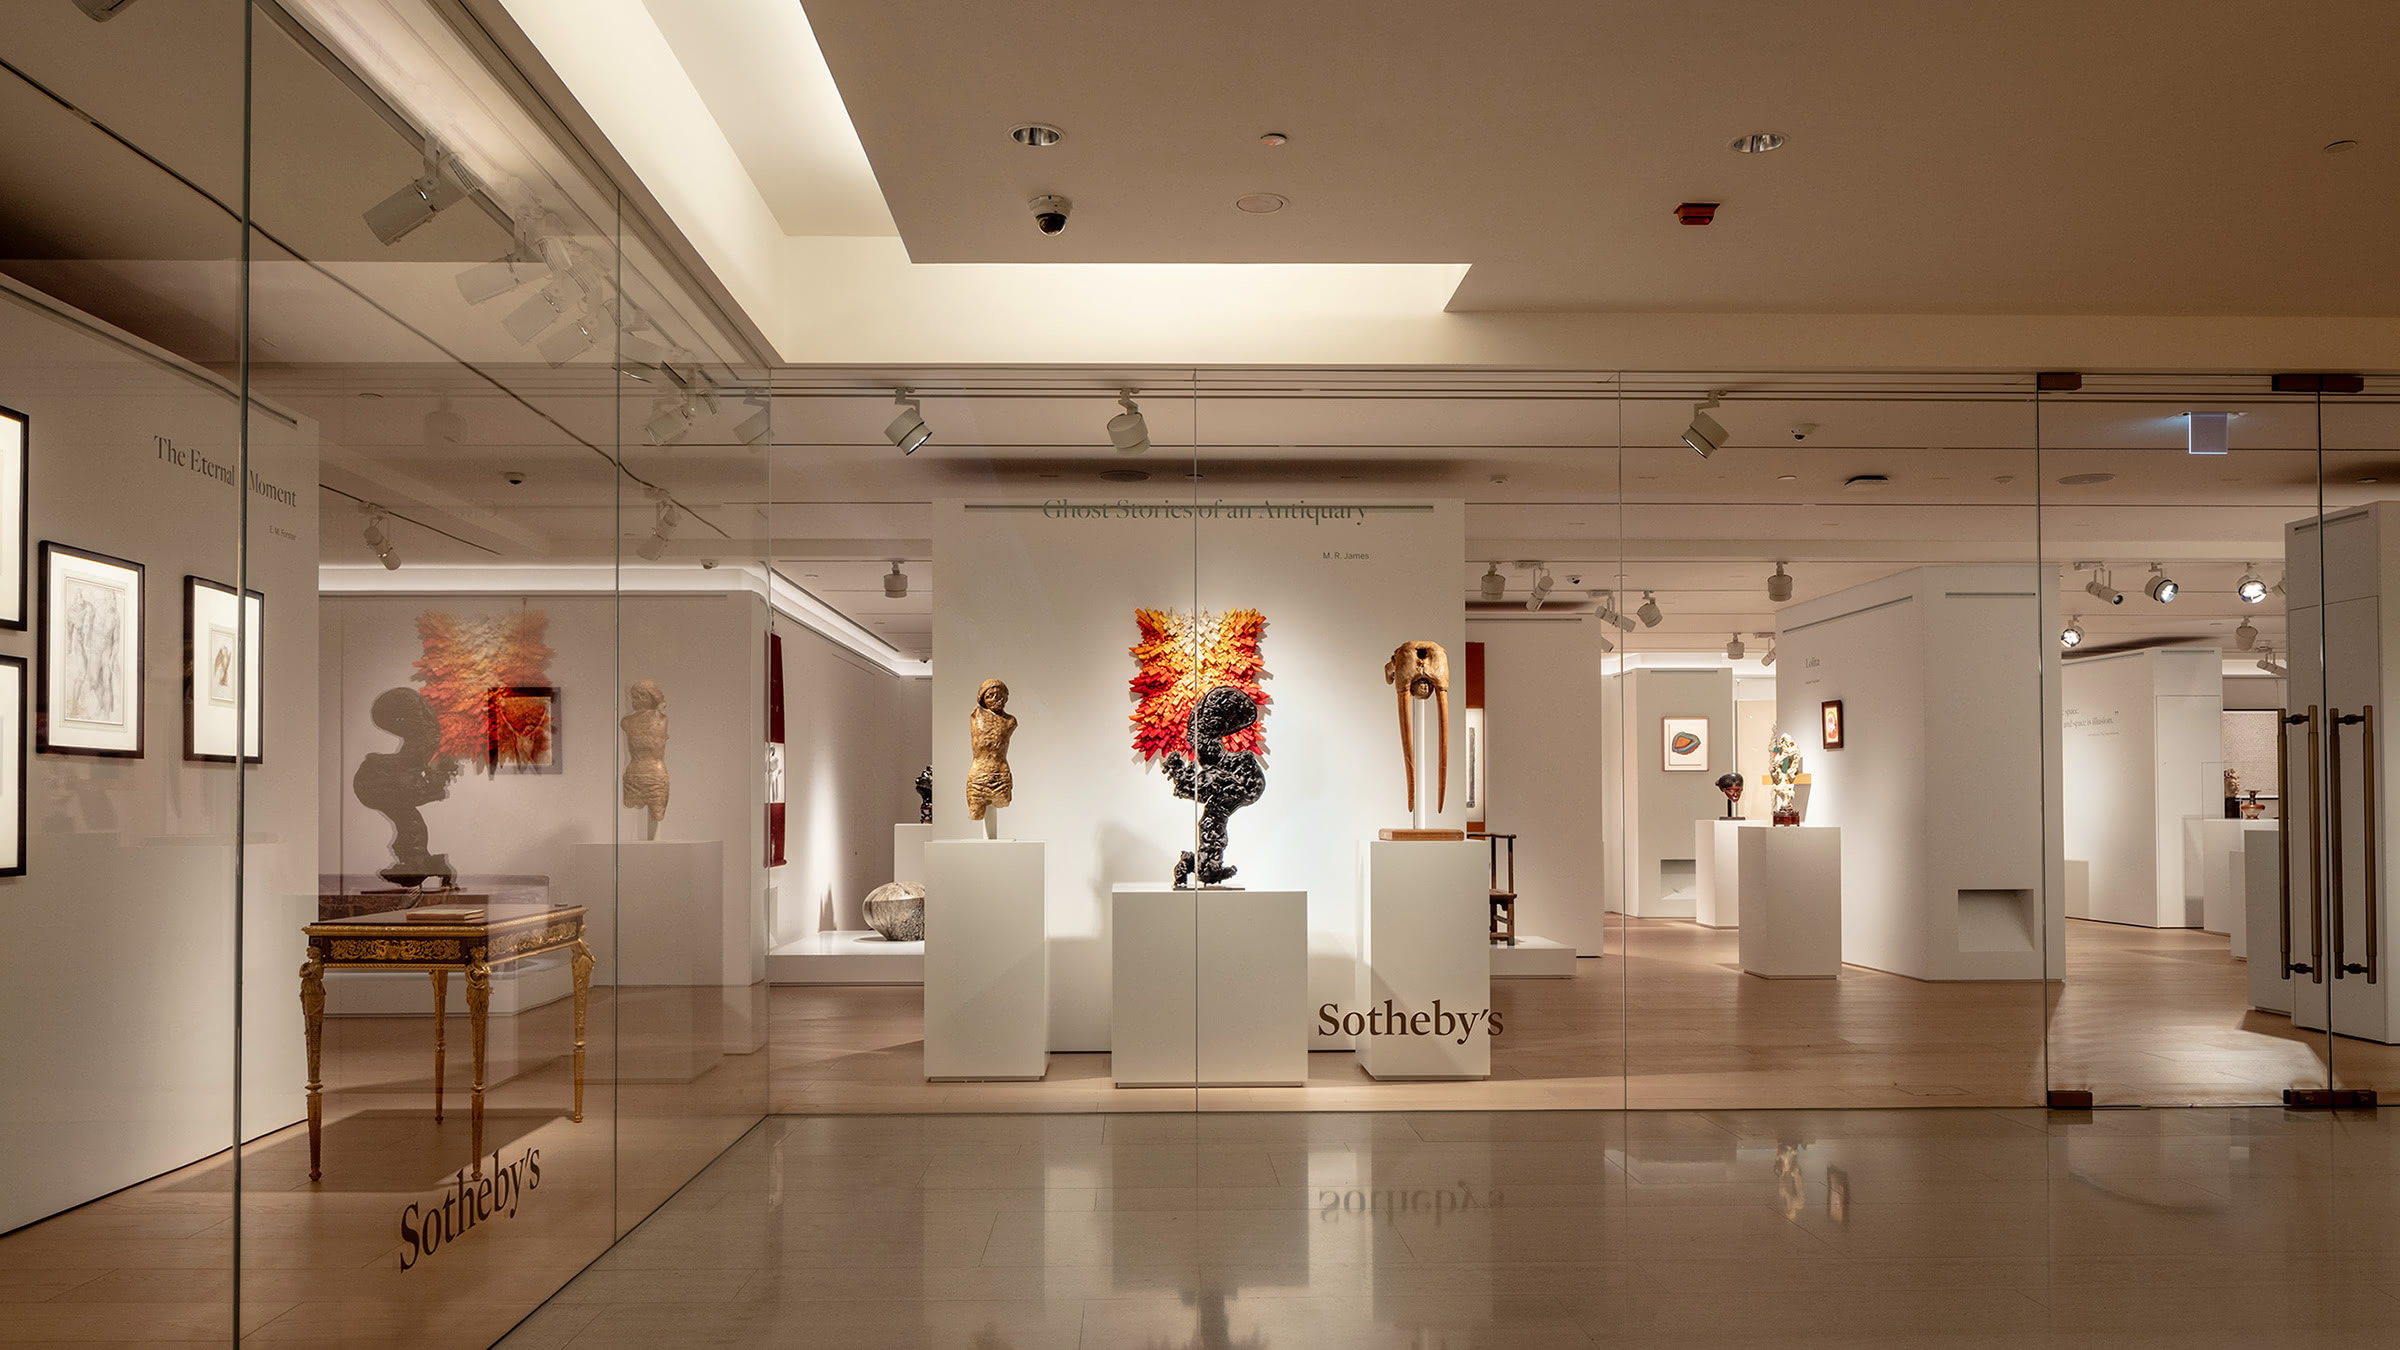
The business will continue to handcraft jewellery at its Newport Beach facility, according to the company. Pieces are sold through boutiques in Miami, Ocala and Aspen, as well as in Newport Beach itself. The new owners said they intend to maintain the strength and continuity of the key management team.
A founder's fraud case
The bankruptcy carried an unusually heavy legal load. Nearly 60 people came forward in court filings claiming they had done deals with Ferder, generally transactions to coinvest in loose diamonds that would be worked into the company's pieces and resold for a profit.
The Securities and Exchange Commission sued Ferder in August, alleging accounting fraud of a scale that led to more than $1 billion in fictitious revenue being booked by the business. The regulator says Ferder ran the scheme from 2021 to 2025, convincing people to invest in diamonds he and Lugano never owned.
Ferder maintains his innocence, and the dispute has drawn in his one-time buyer. Five years ago, Ferder sold a 60 percent stake in Lugano to Compass Diversified Holding at an enterprise value of $256 million. By the time of the Chapter 11 filing, Compass said it was owed $701 million.
A flurry of lawsuits has followed. Jeffrey Reeves, Ferder's lawyer at Reeves & Weiss, argues both Compass and the pre-petition Lugano knew of the financing arrangements, chose to leave them in place and benefited from them, then pinned the blame on Ferder when those practices collapsed on Compass's watch.
Reeves contends the companies took a fabulously successful business into bankruptcy in hopes of evading scrutiny. He says Compass refuses to accept responsibility for poor decisions, and the litigation continues to play out separately from the jeweller's new chapter.
What the new Lugano keeps
The post-bankruptcy company is not involved in that litigation, which gives the new ownership room to operate. The business it inherits is a high-end jeweller known for one-of-a-kind pieces sold to a loyal clientele, with production kept in-house at its California workshop.
Its boutiques stretch across four markets: Newport Beach and Aspen, plus the Florida cities of Miami and Ocala. The geographic spread maps onto the client relationships Kelleher cited, a network the new investors are betting survives the scandal intact.
Gaynor's luxury pedigree is central to the new setup. His time at Bottega Veneta and Fendi gives the company a chief executive familiar with high-end retail, and his continuity through the interim period means the turnaround arrives with leadership already in place rather than a search.
Ferder's alleged scheme, as the regulator describes it, concerned diamonds, coinvestors and revenue booked over four years. The new Lugano is not a party to those claims, and the company has not disclosed what the sale paid or on what terms.
For the new group, the immediate task is the one Gaynor named: reinforcing relationships with the clients whose loyalty helped make the sale possible, and raising the bar for creativity, craftsmanship and personal service. No timeline for further expansion has been disclosed.
Support the content you love — it’s free 🎉
Add Worthbury as a preferred source on Google. Our stories will be more likely to appear in Google’s Top Stories. It’s free and supports our team. Thank you!
Add as preferred sourceYou can remove us any time in Google’s source preferences.
Thank you — you’re all set 🎉
Worthbury is now one of your preferred sources, so our briefings are more likely to appear in Google’s Top Stories.
This briefing is published daily using an AI-powered system crafted by Worthbury's team and finely tuned to meet our editorial standards. While we continuously test and review the output, mistakes can sometimes happen. Tell us if you spot one.
Images: Lugano Newport Beach Courtesy of Lugano; Lugano