Capri Holdings draws buyer interest as $809 million hedge liability looms
John Idol's group has already sold Versace and fought off a blocked Tapestry merger, and now faces a derivative liability nearly four times Tapestry's own.

Capri Holdings has been in contact with prospective buyers who have reviewed the company's books, according to people familiar with the discussions. The process remains informal, and one banker cautioned that a deal would not happen in the near term, but it has advanced far enough for at least some interested parties to take a close look.
Capri owns Michael Kors and Jimmy Choo after selling Versace last year. Michael Kors, founded in 1981 by the designer of the same name, remains the group's largest brand by revenue and the one investors watch most closely for signs of the turnaround Idol has promised.
Chief executive and chairman John Idol built Michael Kors into a large business before adding Jimmy Choo and then Versace to assemble a luxury-leaning group, renamed Capri Holdings from Michael Kors Holdings. A Capri spokeswoman declined to comment on what she called rumours or speculation.
A familiar seat at the deal table
Capri is no stranger to sale processes. In late 2022 the company met with bankers from Barclays and reviewed options including a full sale, an initial public offering of Versace and Jimmy Choo together, or a sale of just the two luxury brands, with bankers describing only a limited number of possible buyers.
One of those buyers, Coach owner Tapestry Inc, approached Idol directly and negotiated an $8.5 billion acquisition of the whole company in 2022. The deal collapsed in late 2024 after antitrust concerns from the US Federal Trade Commission, sending Capri back to the drawing board on its own strategy.
Capri then sold Versace to Prada Group for $1.4 billion last year, using the proceeds to repair its balance sheet. We have previously reported that Prada's price marked roughly a 40% discount to the $2.1 billion Capri paid for Versace back in 2018, reuniting Versace with fellow Milanese house Prada under family control.
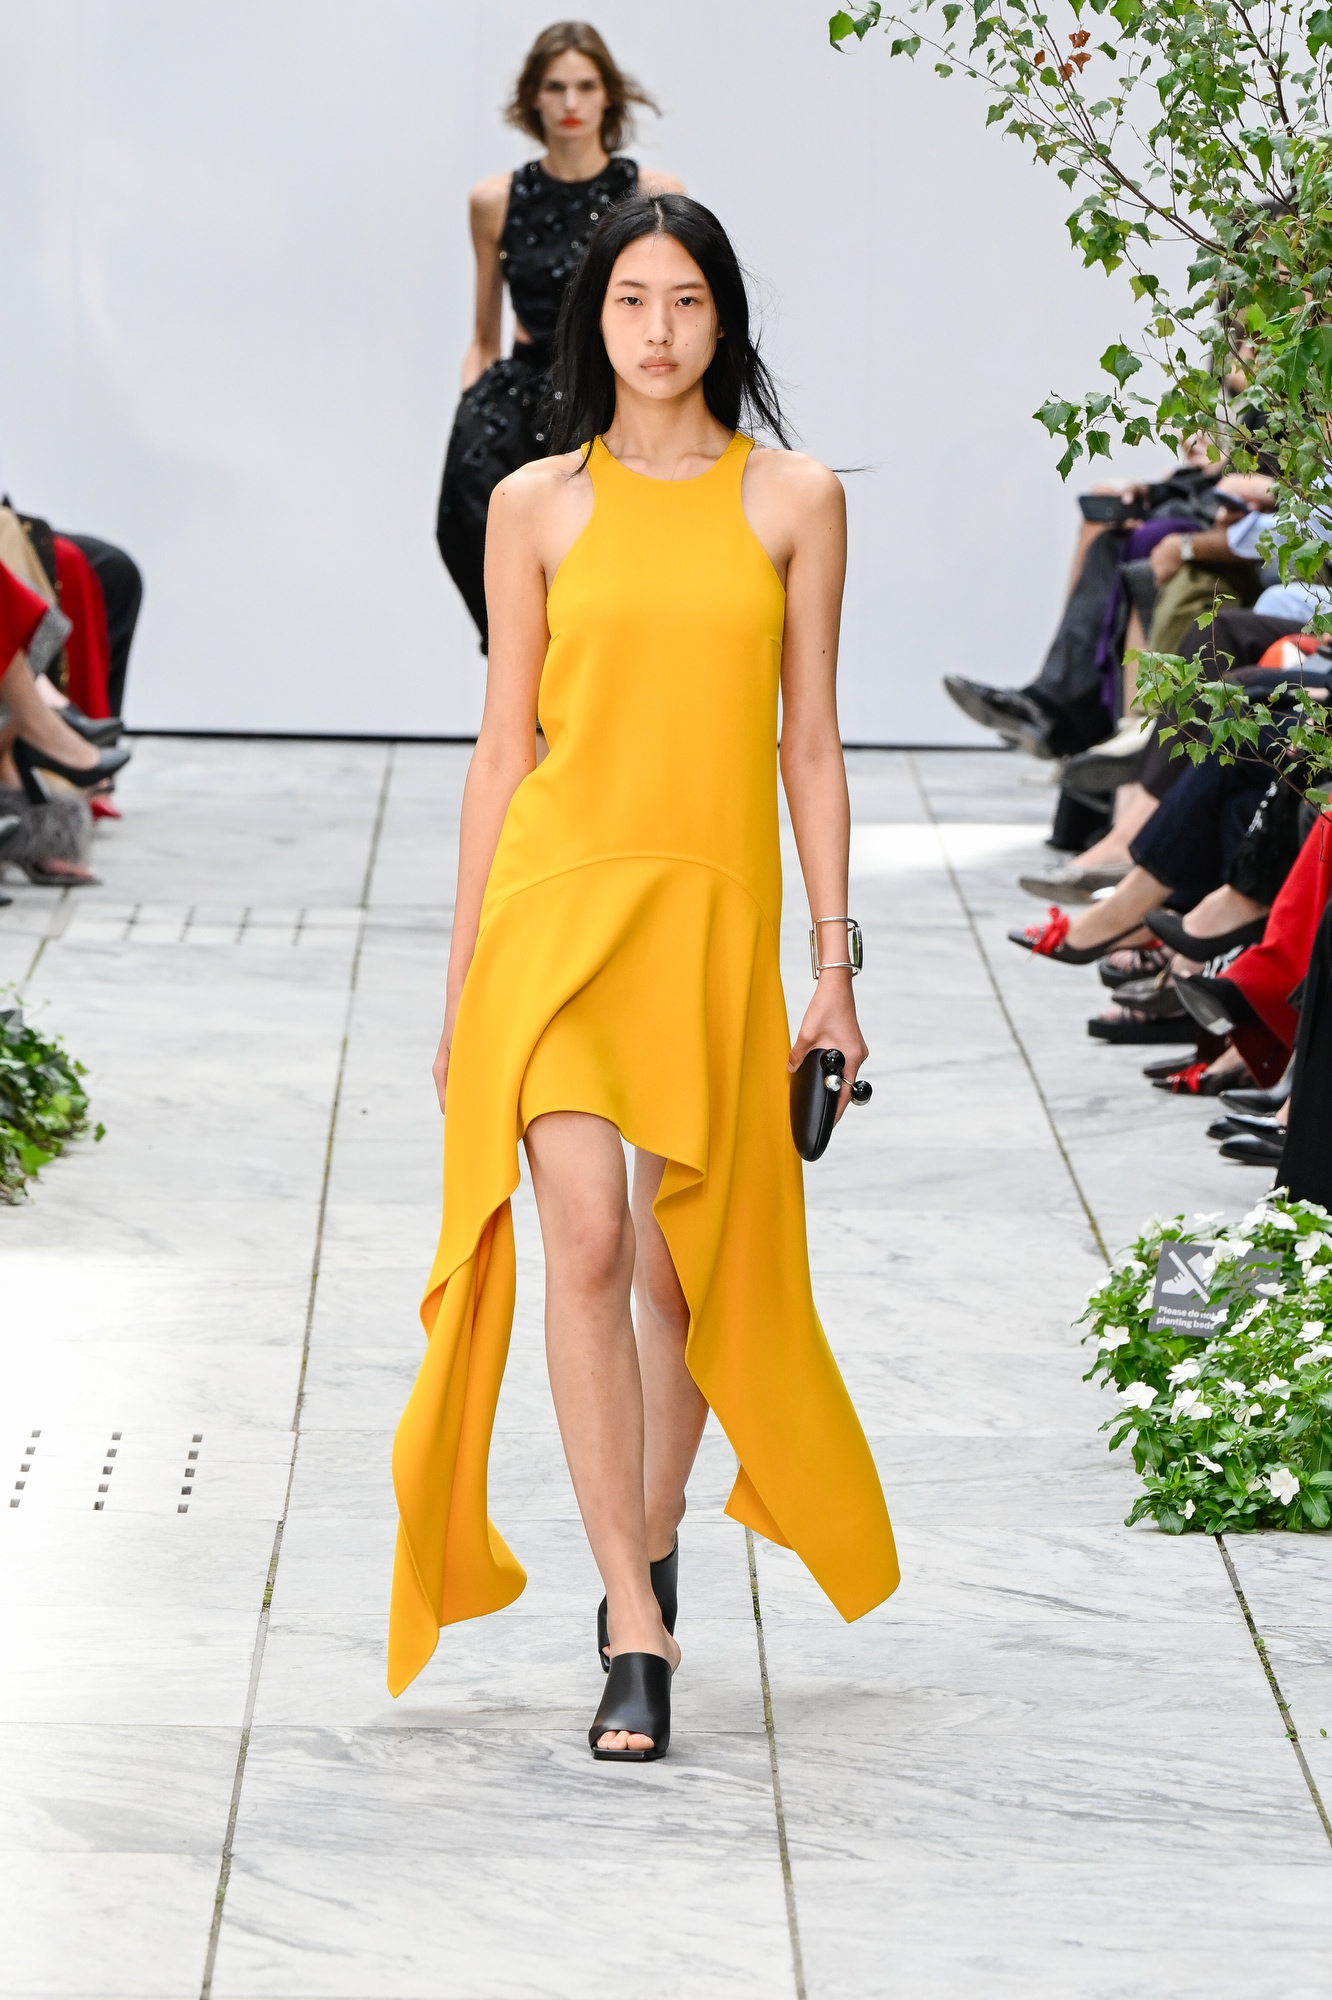
Idol told investors at a conference last week that luxury brands cycle through difficult moments, and that Michael Kors was badly off trend some 18 months ago. The company has since pulled back on price promotions, increased marketing spend and refreshed stores to lay groundwork for renewed growth.
The clearest obstacle is an $809 million derivative liability that would come due immediately if control of the company changed hands. Capri describes the figure as the mark-to-market fair value of its net investment hedge contracts as of June, not a fixed liability, with maturities running from March through 2045.
Those contracts are inside an unusually large currency hedging book: $3.5 billion of fixed-to-fixed cross-currency hedges tied to Capri's Swiss franc exposure and a further $2.4 billion hedging its euro investment, according to a regulatory filing last month. The hedges have also generated $352 million of interest income across the past three fiscal years.
By comparison, Tapestry carries roughly $230 million in derivative liabilities and Ralph Lauren Corp just $13.7 million, leaving Capri's exposure far larger than either rival's. One prospective acquirer was reportedly surprised by the sheer size of the figure, though others see it as a hurdle rather than a dealbreaker.
Attorney and former investment fund manager Jonathan Lazarow said a capable banker could structure around the liability. He argued American investors, unlike LVMH, Kering and Richemont, have little appetite for multi-brand holding companies, and that Michael Kors or Jimmy Choo could each be sold separately.
Why Capri looks cheap to some buyers
Capri's market capitalisation has fallen about 40% this year to roughly $1.7 billion, well below the $10 billion it reached in 2022 and the $20 billion peak it hit in 2014. Guggenheim Securities analyst Simeon Siegel said Michael Kors has become a legacy brand whose market value undersells its scale.
Michael Kors revenue fell 7.1% to $590 million in the first quarter, producing operating income of $55 million and a 9.3% operating margin. Jimmy Choo performed better, with revenue up 10.5% to $179 million, operating income of $13 million and a 7.3% operating margin.
We reported this month that Capri had already dropped a market-capitalisation tier on the same day Nike and Simon Property Group were removed from the S&P 100 Index, underlining how far the group's valuation has slipped from its 2014 and 2022 highs.
Private equity firms have grown wary of fashion investments in recent years, but Capri's depressed stock price could still make it a value opportunity. Brand management companies, which look for well-known names not getting credit for their scale on Wall Street, may also see an opening here.
Lazarow described the logic behind such deals as circular: bankers push consolidation, then years later argue for breaking businesses apart again once it has not worked. What happens next at Capri depends on how Idol, shareholders and prospective buyers each read those same numbers.
This briefing is published daily using an AI-powered system crafted by Worthbury's team and finely tuned to meet our editorial standards. While we continuously test and review the output, mistakes can sometimes happen. Tell us if you spot one.
Images: Capri Holdings